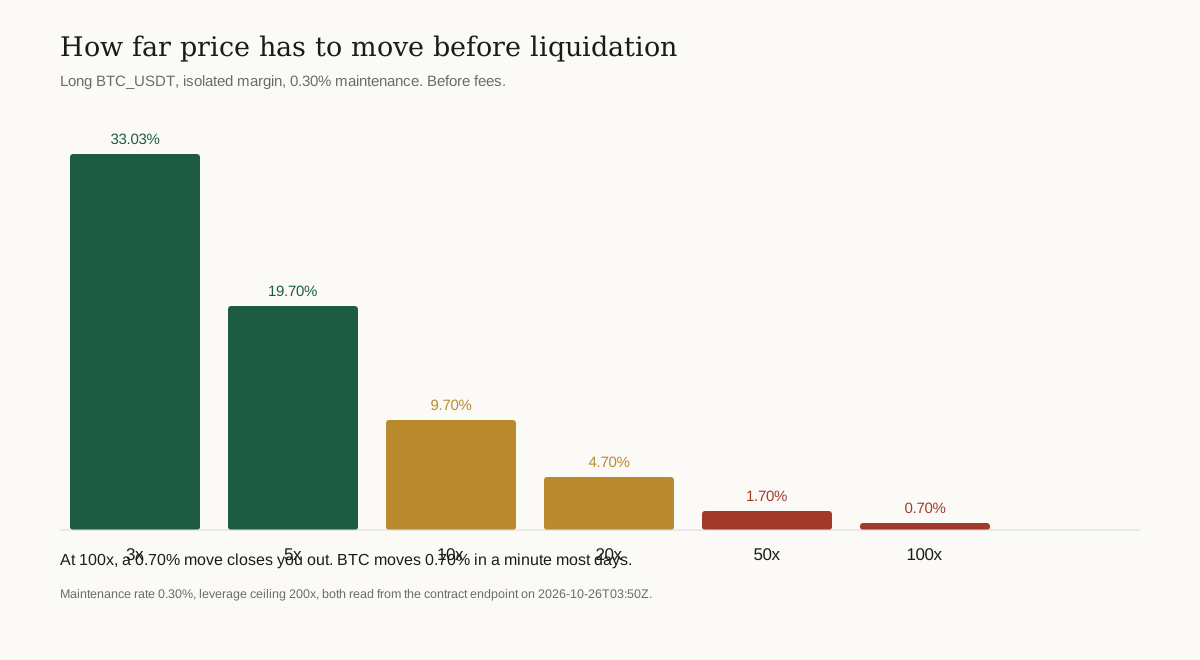
Fifty times leverage on a $2,000 account. Position size $100,000. Same as the trade in every other article here.
The liquidation price is 1.70% away from entry.
BTC moved 1.70% in eleven minutes on a Tuesday, twice.
The fee was never the risk.
Every cost page on this site is about a percentage. Leverage is about a distance: how far the price has to travel before the exchange closes the position for you. That distance is arithmetic, it is published in the contract specification, and almost nobody computes it before sizing a trade.
The distance is one division
On an isolated-margin long, liquidation happens when your margin is used up. The maintenance rate on this contract is 0.30% of notional, charged as a buffer. So the price can fall roughly:
At 50× that is 2.00% minus 0.30% = 1.70%. At 100× it is 1.00% minus 0.30% = 0.70%. At 20× it is 5.00% minus 0.30% = 4.70%.
Note what does not appear in that formula: the fee rate. Fees make the outcome slightly worse but they do not set the distance. Leverage sets the distance.
The whole ladder, before fees
| Leverage | Move that liquidates a long | Position on $2,000 margin | Fee to open at taker rate |
|---|---|---|---|
| 3× | 30.03% | $6,000.00 | $4.50 |
| 5× | 19.70% | $10,000.00 | $7.50 |
| 10× | 9.70% | $20,000.00 | $15.00 |
| 20× | 4.70% | $40,000.00 | $30.00 |
| 50× | 1.70% | $100,000.00 | $75.00 |
| 100× | 0.70% | $200,000.00 | $150.00 |
The fee column grows with leverage because the fee is charged on notional, not on your margin. At 100× you pay $150.00 in fees to control a position whose entire margin is $2,000.00. One 0.70% move against you and the fees are irrelevant, because the position is gone.
Higher leverage is not a bigger position. It is a shorter leash.
This is the part that fee tables get backwards. A 100× limit is listed next to fee rates as if it were a feature of the same kind. It is not a cost advantage and it is not extra buying power in any practical sense — it is a claim on a narrower price path.
Two traders with the same $2,000 and the same conviction can end up with completely different outcomes because one set 20× and one set 50×. Same direction, same entry, same exit target. One survives a normal pullback and one does not.
Where fees do bite: the fee-to-margin ratio
There is one place fees and leverage interact badly. On a $100,000.00 position at 50×, your margin is $2,000.00 and a taker round trip costs $150.00. Add a day of funding and the total is $165.30, against $2,000.00 of margin. You need a 8.26% gain on your margin just to cover the round trip.
That is why high-leverage accounts bleed without an obvious losing trade. The distance to liquidation is 1.70%, and the cost to enter and exit is 8% of your own money. The costs do not need a crash to eat the account; ordinary volatility does it.
Two minutes: compute your own number
- Find the maintenance rate for your contract in the exchange's contract specification. It is a percentage of notional.
- Divide 1 by your leverage, then subtract the maintenance rate. That is the adverse move that liquidates an isolated long, ignoring fees.
- Take 8% off that figure in your head as a safety margin for fees, funding and the difference between mark and last price.
- Compare it to the move the trade needs. If your thesis needs 3% and your liquidation distance is 1.7%, the leverage is wrong, not the thesis.
None of this is a reason to avoid futures. It is a reason to know which number on the screen is the dangerous one. The fee is a rounding error next to the distance.
Where these numbers come from
Measured: Gate contract specification for BTC_USDT — maintenance rate, leverage ceiling and fee rates
Regulator: Investor.gov: leverage explained — why borrowed exposure magnifies losses as well as gains
Regulator: Investor.gov: margin — the definition exchanges assume you already know
Leverage ceilings and maintenance rates vary by contract and change. Confirm yours inside the platform before sizing.
Open a Gate account Referral link — we may earn a commission at no extra cost to you. Gate's services are not available in every jurisdiction; check the User Agreement.Sources
- Gate public REST API, BTC_USDT perpetual: maintenance_rate 0.003, leverage_max 200, mark_price 79449.48. Captured 2026-10-26T03:50Z.
- Liquidation distance computed as (1 / leverage) − maintenance_rate, isolated margin, long side, fees excluded. The fee-buffer adjustment is described in the text and is not applied to the table.
- Regulator glossary definitions from investor.gov, linked above, verified reachable on 2026-10-27.